Cargo insurance protects the financial interest in goods while they move through a transportation supply chain. It can cover physical loss or damage caused by insured events, subject to the policy’s terms, exclusions, deductibles, and declared shipment value. For importers and exporters, the practical decision is whether the potential financial loss from a shipment exceeds the protection available through the carrier’s liability arrangements.
Cargo insurance is separate from a freight carrier’s liability. Carrier liability generally depends on the applicable contract, transport document, governing rules, and circumstances of the loss. It may be limited and does not necessarily reimburse the full commercial value of damaged or missing goods. Before dispatch, the shipper or cargo owner should confirm who arranges coverage, what risks the policy accepts, how the insured value is calculated, and which records an insurer will require if a claim arises.
How Cargo Insurance Works
Cargo insurance transfers specified financial risks from the insured party to an insurer under an agreed policy. The insured party pays a premium in exchange for coverage against defined losses during the policy’s applicable period and within its stated geographical and operational scope.
The policy determines which events qualify for compensation. Depending on the selected coverage, insured events may include accidental physical damage, theft, fire, collision, or other transportation-related incidents. Coverage does not automatically extend to every cause of loss. The insurer evaluates the circumstances against the policy wording, exclusions, conditions, and evidence submitted.
Three financial and contractual elements determine how the protection works:
- Insured interest: The party seeking coverage must have a recognized financial interest in the cargo or otherwise qualify under the policy.
- Insured value: The declared amount establishes the financial basis for coverage, subject to the policy’s valuation method and applicable limits.
- Coverage conditions: The policy specifies insured events, exclusions, deductibles, territorial limits, transit periods, and claim procedures.
The declared value is not automatically the amount an insurer will pay. The final settlement depends on the nature and extent of the loss, the applicable valuation provisions, the deductible, supporting evidence, and any policy limits.
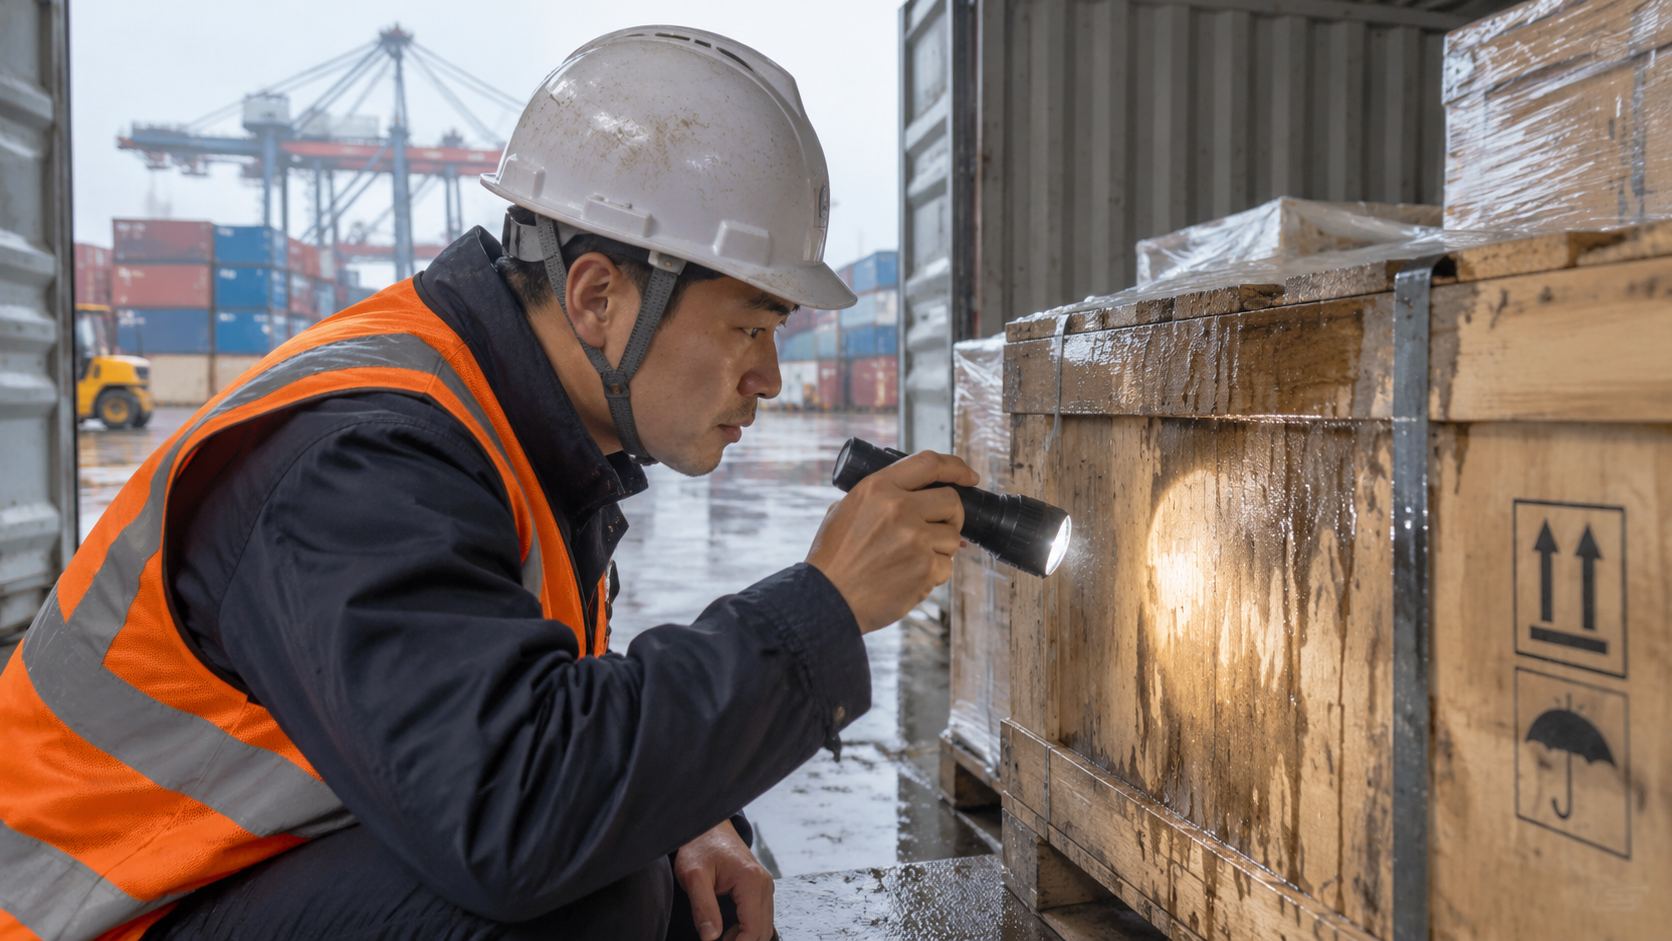
For example, a shipment may arrive with visible water damage after a container experiences an incident during transit. The cargo owner should document the condition, preserve the relevant transport records, and notify the appropriate parties promptly. The insurer then determines whether the event falls within the policy and how the loss should be assessed.
Cargo Insurance vs. Carrier Liability
Cargo insurance and carrier liability address different financial responsibilities. Cargo insurance protects an insured financial interest under a separate insurance contract. Carrier liability concerns the carrier’s responsibility for loss or damage under the applicable transportation contract and legal framework.
This distinction matters because a carrier’s liability may be subject to specific conditions, defenses, exclusions, and monetary limits. A shipper should not assume that a freight booking provides comprehensive protection for the cargo’s commercial value.
| Comparison point | Cargo insurance | Carrier liability |
|---|---|---|
| Primary purpose | Protect the insured financial interest | Address the carrier’s contractual or legal responsibility |
| Basis of protection | Insurance policy wording | Transport contract and applicable rules |
| Financial scope | Subject to insured value and policy limits | May be subject to liability limits and defenses |
| Claim assessment | Insurer evaluates the insured event and loss | Carrier evaluates responsibility under applicable terms |
| Responsible party | Insured or authorized claimant | Party pursuing the carrier’s liability |
A shipper may have grounds to pursue a carrier while also submitting an insurance claim, depending on the contracts and circumstances. The relevant policies and agreements determine how recoveries are coordinated and whether the insurer has recovery rights against a responsible third party.
For a shipment with a high commercial value, relying exclusively on carrier liability may leave a substantial financial exposure. The shipper should compare the potential uninsured loss with the cost and scope of an appropriate cargo insurance policy before dispatch.
What Does Cargo Insurance Cover?
Freight insurance coverage depends on the policy selected rather than the transportation mode alone. Different policies may provide different levels of protection, even when they cover the same shipment and route.
Common coverage considerations include:
- Physical damage: Accidental damage caused by an insured transportation event, subject to exclusions and conditions.
- Total loss: Situations in which the cargo is completely destroyed, lost, or otherwise qualifies as a total loss under the policy.
- Theft or non-delivery: Loss involving theft or missing cargo when the circumstances meet the policy’s requirements.
- Handling incidents: Damage during loading, unloading, or intermediate handling when those activities fall within the insured transit scope.
- Transit-related incidents: Specified risks associated with transportation, including certain accidents or environmental events.
The policy may exclude particular causes of loss or impose additional conditions. Common areas requiring attention include inadequate packaging, inherent defects, ordinary wear, intentional misconduct, delay-related losses, and insufficient preparation for the nature of the cargo. The exact treatment depends on the wording and applicable endorsements.
Shippers should also distinguish physical cargo damage from consequential financial losses. Lost sales, production interruptions, contractual penalties, and delayed market entry may not fall within standard cargo insurance coverage. Businesses with these exposures should ask the insurer whether separate protection is available.
Operator check: Ask the insurer to identify the covered transit period, geographical scope, loading and unloading provisions, exclusions, and any special conditions for the actual commodity. A broad policy description is not a substitute for reviewing its operative wording.
When Should a Business Insure Its Freight?
The decision should reflect the shipment’s financial exposure, transportation conditions, cargo characteristics, and available contractual protection. A business does not need to treat every shipment identically. It should assess the potential loss and the cost of transferring that risk.
- High-value shipments: Insurance may be particularly useful when the cargo’s value substantially exceeds the carrier’s potential liability.
- Fragile or sensitive goods: Products that are vulnerable to impact, moisture, temperature variation, or handling damage may require carefully selected coverage and packaging controls.
- Long or complex transit routes: Shipments involving several transport stages, transfers, or handling points may create additional exposure that warrants review.
- New supplier relationships: Businesses shipping with unfamiliar suppliers or logistics arrangements may have less established operational visibility.
- Time-sensitive inventory: Companies relying on critical stock should distinguish physical cargo protection from business interruption or delay-related protection.
Insurance may be less valuable when the shipment has a low potential loss, an existing policy already covers the movement, or the proposed coverage contains exclusions that directly affect the cargo’s main risks. The buyer should compare the incremental protection with the premium, deductible, and administrative requirements.
Transportation mode also affects the operational review. A business arranging sea freight should check the policy’s treatment of ocean transit, port handling, and any included inland movement. An air freight shipment requires confirmation of the relevant airport handling and transit scope. Businesses using rail freight should verify coverage across the rail journey and any connected transfer stages.
Declared Value and Cargo Insurance Cost
Declared value is a key input when arranging cargo insurance because it establishes the stated financial value of the goods for the proposed coverage. However, declared value can have different meanings across insurance applications, carrier declarations, and transportation documents. A shipper should identify which declaration the provider is requesting before submitting figures.
The appropriate insured value depends on the policy’s valuation provisions. Relevant components may include the commercial invoice value, freight charges, insurance costs, and other eligible expenses. Whether these components can be included depends on the agreement with the insurer.
For an accurate insurance quotation, the shipper should prepare the following information:
- Commodity description and cargo classification.
- Commercial invoice value and currency.
- Shipment weight, quantity, and packaging details.
- Origin, destination, and planned transit route.
- Transportation mode and any connecting movements.
- Requested coverage scope and relevant special handling requirements.
Insurance premiums generally depend on the insured value, cargo type, route, transport conditions, selected coverage, and the insurer’s underwriting assessment. There is no reliable universal premium rate that applies to every shipment. The insurer or authorized insurance provider must confirm the current quotation and applicable conditions.
Illustrative calculation: If the insurer quotes a premium rate of R against an eligible insured value of V, the basic premium calculation may be expressed as:
Estimated premium = V × R
This formula illustrates a percentage-based pricing mechanism only. Actual quotations may include minimum premiums, additional charges, taxes, or other adjustments. The insurer’s quotation determines the payable amount.
A declared value that does not reflect the policy’s accepted valuation basis can create a coverage gap. Confirm the valuation method and insured amount before the insurer issues or confirms the coverage.
Documents and Records That Support an Insurance Claim
Accurate shipment records help establish the cargo’s identity, value, transportation history, and condition. When a loss occurs, the insured party should provide the evidence requested by the insurer and preserve original records wherever practical.
| Record | What it establishes | Responsible party or source |
|---|---|---|
| Commercial invoice | Goods description and transaction value | Seller or exporter |
| Packing list | Package count, contents, and shipment details | Seller or shipper |
| Bill of lading or air waybill | Transport arrangement and shipment identity | Carrier or transport provider |
| Insurance certificate or policy | Insured interest and coverage terms | Insurer or authorized provider |
| Damage photographs and inspection report | Condition and apparent extent of damage | Receiver, surveyor, or other relevant party |
| Claim correspondence and supporting costs | Notification history and claimed financial loss | Insured or authorized claimant |
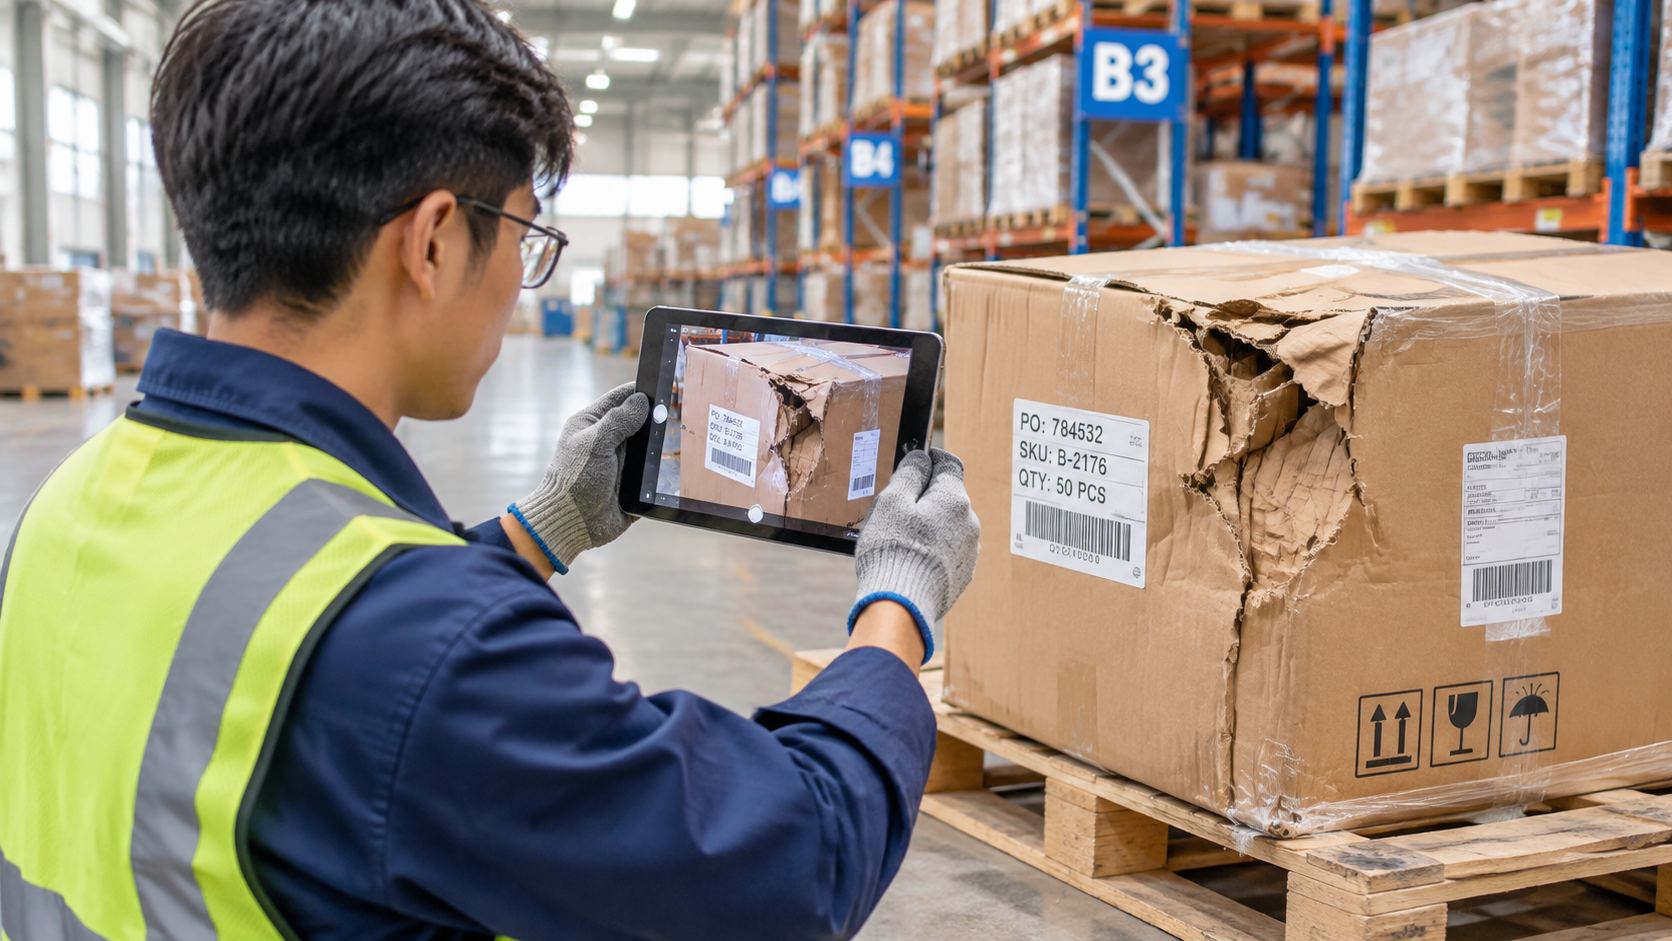
The receiving team should inspect the shipment promptly and record visible damage, missing packages, or discrepancies. Photographs should show the external packaging, shipping labels, damaged goods, and relevant identifying marks. The receiver should also retain delivery records and any written remarks made when acknowledging receipt.
If the shipment arrives with apparent damage, the receiver should notify the carrier and the responsible insurance contact without unnecessary delay. The receiver should preserve the affected packaging and goods until the insurer or appointed surveyor provides further instructions, where practical.
For shipments arranged through multi-modal freight, the shipper should retain records for each transport stage. These records can help establish when the damage occurred and which movement or handling activity requires investigation.
When a business uses door-to-door shipping, it should also confirm whether the insurance covers the complete movement between the stated collection and delivery points. The transport service description alone does not establish the insurance policy’s transit boundaries.
Common Cargo Insurance Mistakes and Operator Checks
Most avoidable insurance problems begin before the shipment moves or immediately after a loss occurs. Shippers should focus on accurate declarations, clear responsibility, and timely evidence collection.
Assuming carrier liability provides full-value protection
A shipper may assume that booking transportation automatically protects the full commercial value of the goods. However, the carrier’s liability and the cargo owner’s insurance protection follow different contractual arrangements. The procurement or logistics team should compare the carrier’s applicable liability terms with the shipment’s financial exposure and arrange additional coverage when appropriate.
Declaring an incomplete or inaccurate shipment value
An incorrect commodity description, understated value, or inconsistent shipment quantity can complicate underwriting and claim assessment. The shipper should reconcile the invoice, packing list, booking details, and insurance declaration before dispatch. Any material change should be reported to the insurance provider for confirmation.
Waiting too long to document damage
Delayed notification or disposal of damaged packaging can make it harder to establish the cause and extent of a loss. The receiving team should document the condition immediately, notify the relevant parties, and follow the insurer’s instructions for inspection and evidence preservation.
Common mistake: Treating an insurance certificate as proof that every shipment risk is covered. A certificate may summarize coverage, but the underlying policy and applicable endorsements determine the operative terms. The shipper should obtain and review the relevant wording before relying on the protection.
Before releasing cargo, the operator should confirm the insured party, shipment description, insured value, route, coverage start and end points, deductible, exclusions, and claim notification procedure. The insurer or authorized provider should resolve any uncertainty in writing.
Disclosure: This guide provides general logistics information and may refer to services relevant to the topic. Carrier terms, customs requirements, fees, service coverage, and operating conditions can change. Confirm current requirements and responsibilities before acting.
Key Takeaways
- Cargo insurance protects an insured financial interest against specified transportation-related losses, subject to policy conditions.
- Carrier liability is separate from cargo insurance and may not cover the full commercial value of the shipment.
- The declared value should follow the insurer’s accepted valuation method and match the shipment records.
- Coverage should reflect the cargo, route, transportation mode, handling requirements, and potential financial exposure.
- Commercial invoices, packing lists, transport documents, insurance records, and damage evidence support claim assessment.
- Shippers should confirm policy wording, exclusions, deductibles, transit boundaries, and notification procedures before dispatch.
Frequently Asked Questions About Cargo Insurance
What is cargo insurance in international shipping?
Cargo insurance is financial protection for goods moving through an international transportation chain. It covers specified physical losses or damage according to the policy’s terms, exclusions, and insured value. The shipper should confirm whether the policy covers the complete route, including connecting transport and handling stages.
Is cargo insurance the same as freight insurance?
The terms freight insurance and cargo insurance are often used interchangeably in logistics discussions. Both commonly refer to insurance protecting goods during transportation. However, the actual protection depends on the policy wording, so the buyer should review the insured interest, covered events, and exclusions rather than rely on the product name.
Does cargo insurance cover damaged goods?
It may cover damaged goods when the damage results from an insured event during the covered transit period. The insurer evaluates the cause, policy exclusions, packaging conditions, and supporting evidence. The receiver should photograph the damage, preserve relevant records, and follow the insurer’s inspection instructions.
Does freight insurance cover delays?
Standard cargo insurance primarily addresses insured physical loss or damage rather than every financial consequence of a delay. Lost sales, missed production deadlines, and contractual penalties may require separate protection. The buyer should ask the insurer whether any delay-related coverage applies to the specific policy.
How is cargo insurance calculated?
The premium commonly depends on the insured value, cargo type, route, transportation conditions, and selected coverage. Some quotations use a percentage of the accepted insured value, while others may include minimum premiums or additional charges. The insurer must confirm the applicable rate and final quotation.
What does declared value mean in cargo insurance?
Declared value is the financial amount submitted for insurance consideration under the relevant valuation method. It may be based on the commercial value of the goods and other eligible costs, depending on the policy. It does not automatically establish the final claim settlement amount.
Who is responsible for arranging cargo insurance?
The responsible party depends on the sales agreement, shipping arrangement, and insurance contract. A buyer or seller may arrange coverage, or an authorized logistics provider may help coordinate it. The parties should confirm who purchases the policy, who is insured, and who receives the insurance documents before shipment.
What should I do if my shipment arrives damaged?
Document the damage immediately with photographs, package details, and delivery records. Notify the carrier and insurance contact promptly, preserve the damaged goods and packaging where practical, and request inspection instructions. Submit the invoice, packing list, transport document, insurance records, and other evidence requested by the insurer.
Disclaimer: This article is general informational guidance, not a binding quotation, legal opinion, customs ruling, carrier commitment, or delivery guarantee. Requirements, charges, service terms, and responsibilities can vary by route, cargo, contract, carrier, and jurisdiction. Confirm current requirements before booking or filing.