When Air Freight Cargo Insurance Changes the Shipment Decision
Air freight cargo insurance becomes most useful when the financial exposure from loss, damage, mishandling, or an uncovered shipment risk is more important than the cost and effort of arranging protection. The practical decision is not simply whether to insure the cargo. It is whether the proposed freight insurance coverage matches the cargo value, packing condition, handling path, evidence requirements, and exclusions that apply to the shipment.
Buyers should separate transport from protection. A carrier or forwarder may provide a transport service without providing broad cargo insurance, and declared value does not by itself prove that a shipment has full insurance coverage. The quote should therefore identify the insured scope, valuation basis, exclusions, claim documentation, and the point at which risk transfers between parties. For high-value, fragile, time-sensitive, or difficult-to-replace goods, international shipping insurance can be a useful risk-control layer when the policy terms fit the actual air-freight movement.
Which Air Shipments Need Closer Insurance Review?
The strongest candidates are shipments where a physical loss or damage event would materially affect the buyer’s commercial position. Electronics, precision equipment, replacement components, samples with high unit value, fragile goods, and cargo with expensive packaging or testing requirements deserve a closer review. The same applies when a shipment passes through several handlers or when the buyer has limited ability to replace the goods quickly.
Insurance becomes a weaker fit when the shipment value is modest, the cargo is easily replaceable, the commercial exposure is already covered elsewhere, or the proposed policy exclusions remove the principal risks. A buyer should also check whether the cargo requires special handling or project planning before treating insurance as the main control. Standard air freight may not be the right operational path for cargo that exceeds normal handling constraints; a specialist project cargo shipping service may need to be considered first.
| Shipment condition | Insurance focus | Decision checkpoint |
|---|---|---|
| High-value cargo | Coverage limit and valuation | Confirm the covered value |
| Fragile or sensitive goods | Packing and damage exclusions | Match packing evidence to policy terms |
| Multiple handling points | Handling and evidence trail | Record condition at handoffs |
| Time-critical replacement cargo | Loss exposure beyond transport cost | Check whether delay is actually covered |
| Restricted or controlled goods | Eligibility and exclusions | Confirm cargo admissibility before booking |
Field note: If the commercial invoice, packing list, product description, and declared value do not describe the shipment consistently, stop the insurance request and reconcile the shipment data before booking. A clean data set makes the coverage review and any later claim investigation easier.
How the Air Freight Route Affects Insurance Coverage
The insurance decision should follow the physical movement of the cargo. The buyer first identifies the pickup point, export handoff, airport handling chain, main air movement, destination handling, customs release, and final delivery scope. Each handoff creates an evidence point, so the insurance review should match the actual service pattern rather than rely on a generic description such as “air freight.”
For standard airport-based cargo, compare the proposed protection with the exact air freight service, including who receives the cargo, who controls the shipment record at each transfer, and where destination delivery begins. A door-to-door move requires the buyer to examine more than the aircraft leg because pickup, terminal handling, customs, and final delivery form part of the physical chain. The relevant door-to-door shipping scope should therefore be stated in the quote.
A parcel-style shipment may follow a different handling and claims process. When the shipment uses express shipping, review the carrier’s own coverage terms separately instead of assuming that an air-freight cargo policy applies in the same way. A shipment that moves through more than one transport mode also needs a clear responsibility boundary, so a multimodal freight plan should identify which policy and claim process governs the cargo across the combined movement.
The route is a weak fit for a generic insurance request when the cargo description, handling requirements, destination delivery scope, or product controls remain unclear. The buyer should settle those operational inputs first, then compare insurance terms against the actual shipment path.
How to Read Air Transit Timing Without Confusing It With Insurance
Insurance and transit planning solve different problems. Transit planning measures how the shipment is expected to move; insurance addresses defined financial risks under the policy terms. A faster service can reduce the time cargo spends in transit, but faster movement does not automatically create broader freight insurance coverage or eliminate handling, packing, or exclusion risks.
For a quote, ask the freight team to identify the specific airport-to-airport pair, service pattern, and whether any quoted timing represents main carriage only or the full door-to-door cycle. The same distinction should appear in the shipment record used for the insurance review. If pickup, export handling, customs processing, or final delivery sits outside the stated transit measure, those stages should not be treated as part of the transport figure without confirmation.
The practical timing drivers include flight availability, routing structure, transfer points, airport handling, export and import clearance, shipment readiness, and final-mile constraints. Peak capacity can tighten operating windows, while incomplete documents or additional cargo checks can extend the cycle. These factors should be confirmed with the carrier, broker, or forwarder for the specific booking rather than assumed from a generic service description.
What Should a Cargo Insurance Quote Actually Cover?
A useful insurance quote should let the buyer compare protection against the shipment’s real financial exposure. Start with the cargo description and the valuation basis, then identify the insured scope, applicable exclusions, deductible or excess where relevant, claim evidence requirements, and the point at which cover begins and ends. The buyer should not treat the presence of an insurance line on a freight quote as proof that every loss scenario is covered.
Declared value is an important shipment input, but it should be handled carefully. It may be used in the commercial and transport documentation while the insurance valuation method follows the policy terms. The buyer should therefore ask which value is being insured, which documents support that value, and whether additional components of the commercial exposure are recognized under the policy. An invoice value and an insured value should not be treated as automatically interchangeable.
Review the freight quotation and insurance wording together. Transport charges may cover some combination of pickup, export handling, main freight, destination handling, customs, and delivery, but the exact included scope depends on the carrier, route, and quotation. Duties and taxes are a separate commercial question from physical cargo protection. When a service uses a duty-and-tax handling arrangement, the buyer should distinguish that scope from insurance and review the DDP shipping service separately.
For customs-facing shipments, insurance does not replace accurate product classification, commercial documentation, or import-entry work. The buyer should coordinate the coverage request with the customs file so that the shipment description, value, consignee, and supporting records remain consistent. Where a specialist entry process is required, the relevant customs brokerage service should be part of that operational check.
Ask the quote provider to state whether coverage applies to physical loss, physical damage, handling events, theft risks, water exposure, breakage, or other named risks, and ask which exclusions could materially change the result. Delay, ordinary wear, inadequate packing, inherent characteristics of the goods, and certain restricted circumstances may receive different treatment depending on the policy. The buyer should verify the exact wording rather than infer coverage from a general label.
Note: Freight rates change with cargo details, route, carrier capacity, fuel costs, seasonal demand, service scope, and destination charges. Request a current quote for the specific shipment.
Where Insurance Fits Into the Shipping Process
The insurance decision should be completed alongside the shipment file, not after the cargo has already moved without a clear coverage record. Each handoff should leave a usable trail for the freight team, insurer, and buyer.
Request Quote
The buyer supplies the cargo description, value, packing details, pickup and delivery scope, and any special handling needs. The verification point is a written statement of the proposed coverage, valuation basis, and exclusions.
Cargo Pickup
The pickup party confirms package condition, marks, labels, packing, and quantity against the shipment records. The verification point is a consistent cargo record before the first custody handoff.
Export Customs Clearance
The shipper provides accurate commercial and product information for export filing. The verification point is that the shipment description and declared value used in the freight file remain consistent with the supporting documents.
International Transportation
The carrier moves the shipment under the booked air service. The carrier issues the master air waybill, while a forwarder may issue its own house air waybill. The verification point is that the transport documents match the cargo and routing record.
Destination Customs Clearance
The importer or its appointed customs party supplies the required entry data and supporting documents. The verification point is that customs information, cargo value, consignee details, and any product controls align with the shipment file.
Final Delivery
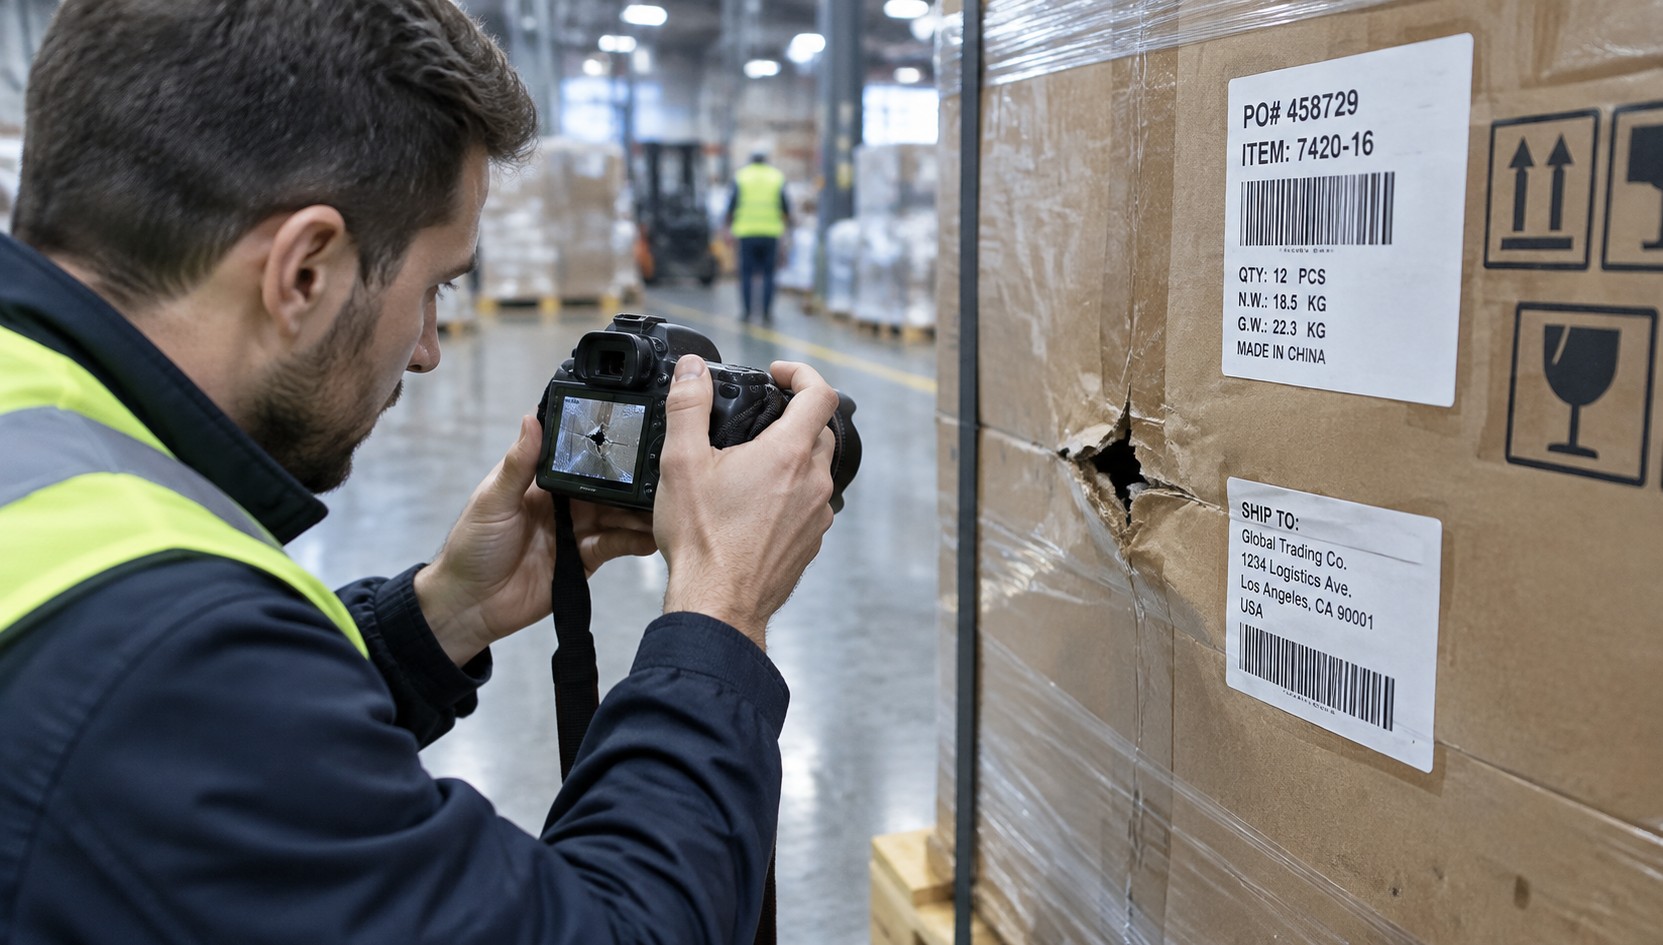
The delivery party checks the outer condition and records visible loss or damage before accepting the cargo where practical. The verification point is prompt documentation of exceptions and preservation of relevant shipment evidence.
Which Insurance Risks Deserve Preventive Controls?
The most useful controls address the gap between the cargo’s actual exposure and the protection the buyer believes it has. The shipment file should make the cargo identifiable, the value supportable, the packing condition observable, and the handoffs traceable.
Value mismatch: Reconcile the declared value, commercial documents, and insurance valuation basis before booking so the buyer knows what amount the policy is intended to address.
Packing-related loss: Review whether the packaging is suitable for the cargo and whether inadequate packing could fall within an exclusion under the proposed policy.
Weak handoff evidence: Keep shipment records, package condition evidence, transport documents, and delivery exceptions together so a claim review does not depend on memory.
Coverage assumption: Read exclusions and claim conditions before booking instead of relying on the words “insured” or “covered” alone.
Common mistake: Buying insurance based only on the cargo’s declared value and never checking what happens when the shipment is delayed, repacked, handled by multiple parties, held for customs, or delivered with visible damage. The better approach is to test the policy against the actual movement and the evidence the buyer can produce.
Air cargo insurance needs a separate review when the shipment contains restricted, controlled, unusually fragile, temperature-sensitive, or otherwise specialized goods. Confirm eligibility, packing standards, and exclusions with the insurer and freight team before the cargo enters the transport chain.
Disclosure: This page provides general route-planning information and may mention freight services available through this website. Transit times, freight costs, customs requirements, carrier schedules, and destination conditions can change. Confirm the current shipment plan before booking.
How to Prepare the Right Insurance Request
The practical default is to review cargo insurance when the financial consequence of physical loss or damage would be significant relative to the shipment’s commercial value and replacement difficulty. The default changes when another policy already covers the exposure, when the proposed exclusions remove the main risks, or when the cargo falls outside the insurer’s acceptable conditions. The quote should follow the actual freight path rather than use a generic insurance description.
For valuable or hard-to-replace cargo: request written confirmation of the valuation basis, insured scope, exclusions, and claim evidence before booking.
For fragile cargo: provide packing specifications and ask whether packaging condition affects eligibility or claim treatment.
For door-to-door movement: define the physical delivery scope clearly so insurance review follows the full handling chain rather than only the aircraft leg.
For specialized or controlled cargo: confirm admissibility and exclusions before cargo pickup, because insurance cannot solve an underlying transport-eligibility problem.
To prepare a useful quote request, provide the product description, declared value, commercial documents, packing method, package marks, pickup and delivery locations, requested service scope, cargo characteristics, and any known handling or product-control restrictions. State whether customs clearance or final delivery is part of the requested service so the freight team can distinguish transport scope from insurance scope.
Illustrative example (not a customer case): A buyer is moving delicate commercial equipment on an air route where replacement is difficult. The standard insurance review fits because the cargo is financially sensitive and the buyer can provide clear product and packing records. The decision flips when the proposed policy excludes the principal damage scenario for that equipment, in which case the buyer should reassess the packing, service path, and available protection before booking.
Key Takeaways
- Choose insurance by the cargo’s actual financial exposure, not by the presence of an insurance line on a freight quote.
- Keep transport scope and insurance scope separate so the buyer knows which part of the movement each term addresses.
- Treat declared value as a shipment input that must be reconciled with the policy’s valuation basis.
- Review exclusions, packing conditions, and claim evidence before cargo pickup.
- Match the insurance review to every material handoff in the actual delivery chain.
FAQ
Does cargo insurance automatically cover shipment delays?
No. Physical loss or damage protection and delay-related financial protection are different issues. A buyer should not assume that a delayed delivery, missed sales opportunity, or production interruption is covered simply because the cargo itself is insured. Ask for the policy’s treatment of delay and related exclusions before relying on insurance for time-sensitive business exposure.
Is declared value the same as the value used for insurance?
Not necessarily. Declared value is a shipment input, while the insurance policy may define its own valuation method and supporting evidence. The buyer should ask which value the insurer will use, which documents establish that value, and whether the commercial figure supplied to the freight provider is consistent with the policy terms.
Can I arrange insurance after the cargo has already been shipped?
Do not assume that coverage can be added retrospectively. Eligibility, attachment of coverage, and notification requirements depend on the insurance arrangement. The safest process is to disclose the shipment before movement and obtain written confirmation of when the protection starts. A freight team should confirm the timing directly rather than relying on a general assumption.
Does air freight insurance replace the carrier’s liability?
No. Cargo insurance and carrier liability are different mechanisms with different terms, limits, exclusions, and claim procedures. A buyer should review both rather than treating one as a substitute for the other. The transport documents also matter because they establish the shipment record, while an insurance policy governs the separate coverage being purchased.
What evidence is useful when cargo arrives damaged?
Useful evidence normally includes the shipment documents, package identification, records showing the cargo’s condition, photographs or other condition evidence, delivery exceptions, and supporting commercial records. The exact claim file depends on the policy. The important operational point is to document the condition promptly and preserve the evidence instead of discarding damaged packaging.
Does better packaging guarantee an insurance claim will be accepted?
No. Better packaging can reduce preventable damage, but claim decisions still depend on the policy wording, the cause of loss, exclusions, evidence, and other applicable conditions. Packaging should therefore be treated as a preventive control rather than a promise of claim acceptance. The buyer should confirm specific packing requirements before the shipment moves.
Is insurance useful for low-value air freight?
It can be, but the decision depends on the commercial consequence of a loss rather than cargo value alone. A low-value component can still be important when it interrupts production or is difficult to replace. The buyer should compare the actual exposure, available existing protection, policy conditions, and administrative effort before deciding.
Disclaimer: Transit times, cost explanations, customs information, and shipping suggestions on this page are general planning references, not a binding quotation, customs ruling, or delivery guarantee. Confirm the current route, service scope, charges, documents, and import requirements before booking.