When Does Sea Freight Insurance Beat Relying on the Carrier?
Sea freight insurance gives the cargo owner a claim against an insurer when goods are lost, damaged, or caught in a general average event at sea. Most commercial shipments should carry a separate cargo policy, because the carrier’s liability is limited by contract terms and excludes many causes of loss that a policy can cover. The decision to settle before booking is which party buys cover, on what value, and from which point to which point.
The trade-off is premium against exposure. Broader cover costs more and demands accurate shipping documents, while narrow cover or none leaves the owner absorbing losses from rough handling, theft, water damage, or a vessel casualty. The right level depends on who carries risk under the sales contract, what the cargo is worth, and how it is packed and handled.
Which Shipments Justify Separate Cover, and Which Can Skip It?
Separate cover earns its premium when the cargo costs more to replace than carrier liability would repay, or when a bank, buyer, or contract requires it. High-value electronics, machinery, and fragile goods fit, as do LCL shipments that pass through consolidation and deconsolidation warehouses and face more handling.
The sales term decides who must act. Under FOB, the buyer carries risk once the cargo is on board and normally arranges cover. Under EXW, risk moves earlier, so the buyer’s cover should start at the seller’s premises. Under CIF, the seller buys cover at a minimum level, and the buyer should check whether that level protects the cargo’s full commercial value.
Weak fit: Low-value cargo that the owner can replace easily, where premium and claim effort exceed the expected loss.
Weak fit: Cargo already inside the owner’s annual open cover. Confirm the overlap so the shipment is not insured twice.
Specialist review first: Dangerous goods, used goods, and deck cargo. Raise them with the underwriter before booking.
Field note: When a supplier on FOB or EXW terms offers to add insurance, ask for the policy wording and the insured party’s name before agreeing. A certificate that names only the supplier leaves the importer unable to claim unless the interest is assigned.
How Does Cover Follow the Cargo Across Legs and Handoffs?
Freight insurance coverage is defined by the policy’s transit clause and named perils, not by the transport mode. The first test is where cover starts and stops. A warehouse-to-warehouse clause is designed to follow the cargo from its first movement at the seller’s site to the final delivery point, but the wording sets the exact limits, including any time limit for storage after discharge.
A port-to-port sea freight booking leaves pickup trucking, terminal storage, and inland delivery outside the carrier’s contract, so the policy must name those legs. FCL cargo stays sealed between stuffing and unloading, which puts the packing standard at the shipper’s door. LCL cargo is handled at consolidation and deconsolidation points, which raises handling exposure.
When the cargo changes mode, such as truck to vessel to rail, the policy must name each leg. Multi-modal freight movements add handoffs between carriers, so each handoff needs a custody record that shows the cargo’s condition.
Cover can fail on conditions the shipper controls: undeclared dangerous goods, packing that is inadequate for sea transport, or a vessel or stowage method outside the policy’s conditions. Oversized cargo shipped on deck or as break-bulk needs underwriter approval before booking.
How Long Does Cover Run, and When Must It Be Arranged?
Timing matters in two ways: when cover attaches and how long it lasts. Cover must be in place before the cargo starts moving, because an insurer will not accept a loss that is already known. Arrange it before handover to the first trucker or carrier, not at vessel loading.
Main-carriage duration depends on the specific port pair and service pattern, so the forwarder should confirm sailing time for that pair. Size the cover to the longest realistic exposure, including port dwell, transshipment waits, and customs holds, not to the scheduled sailing alone.
| Checkpoint | What to confirm | Timing driver |
|---|---|---|
| Before handover | Insured value, clauses, certificate wording | Document readiness, underwriting questions |
| At loading | Bill of lading details match the certificate | Carrier’s bill issue time |
| During ocean carriage | Cover continues through delays and transshipment | Port pair, service pattern, congestion |
| After discharge | Storage time limit in the policy | Customs clearance, pickup speed |
| At delivery | Exception notes and claim notice | Consignee inspection, carrier receipt |
As a planning reference, allow roughly 3 to 4 business days before cargo handover to confirm insured value, clauses, and certificate wording. Peak-season workloads and special cargo can lengthen that window, so ask the forwarder for the current lead time.
Which Shipping Documents and Checkpoints Support a Claim?
Insurance, customs, and claims all draw on the same shipping documents, so a mismatch in one surfaces in the others. The commercial invoice, packing list, and bill of lading should agree on cargo description, quantity, consignee, and marks. A negotiable bill of lading functions as a document of title, so a letter of credit may require the insurance certificate to be endorsed and presented with it. Whoever files the entries, including a customs broker working through customs brokerage, should receive the same invoice values and descriptions that the insurer holds.
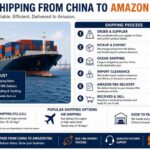
Request Quote
The cargo owner or its forwarder submits insured value, commodity, packing, sales term, and route to the insurer. Verify that the written quote lists clauses, deductible, and start and end points.
Cargo Pickup
The shipper hands packed cargo to the trucker or consolidator and records its condition with photos and a signed receipt. Verify that the policy starts at this handover point.
Export Customs Clearance
The exporter or its broker files the export declaration. Verify that invoice and packing list data match the cargo description given to the insurer before filing.
International Transportation
The carrier issues the master bill of lading, and the forwarder may add a house bill. Verify container numbers, consignee, and description against the certificate before the bill is released.
Destination Customs Clearance
The importer or its customs broker files the import entry and arranges pickup. Verify that declared values reconcile with the insured value basis and that port storage stays within the policy’s time limit.
Final Delivery
The consignee inspects the cargo on arrival and notes any exceptions on the delivery receipt before signing. Verify that photos, packaging, and seal details are preserved and that the insurer receives prompt notice.
What Does Ocean Freight Insurance Leave Uncovered, and How Do You Control It?
Standard cover excludes several losses that cargo owners often assume are included. Insurers typically decline claims caused by insufficient packing, inherent vice such as natural deterioration of the goods, and delay. Control these by packing for sea carriage, recording packing condition at handover, and planning separately for late delivery.
Underinsurance reduces recovery. If the insured value falls below the cargo’s actual value, a claim can be settled below the loss, and misdescribed cargo can give the insurer grounds to contest it. Set the value basis in writing and describe the cargo as it appears on the commercial invoice.
General average is a sea-law principle under which cargo owners contribute to losses the shipowner incurs to save the voyage. A marine policy usually responds to that contribution, but the carrier may withhold delivery until security is posted, so the owner needs the policy details at hand.
Common mistake: Treating the carrier’s bill of lading liability as insurance. That liability is capped by package or weight, subject to carrier defenses, and claims against the carrier carry short filing limits, so the owner can recover far less than the loss.
Risk alert: If the carrier or its agent declares general average, send the notice and the policy to the insurer before signing any guarantee or bond.
Disclosure: This page provides general route-planning information and may mention freight services available through this website. Transit times, freight costs, customs requirements, carrier schedules, and destination conditions can change. Confirm the current shipment plan before booking.
Which Cover Should You Choose, and What Should You Send for a Quote?
The practical default is warehouse-to-warehouse cover under all-risks style clauses, written in the owner’s name, on the invoice value plus freight, with war and strikes clauses added. Shippers with regular volume may place an annual open cover instead of insuring each shipment separately.
Change that default when a fact changes. Choose narrower named-perils cover when the cargo is robust and well packed and the owner accepts more risk. Follow letter of credit wording exactly when a bank is involved, even where it differs from the default. Add a top-up when a seller’s minimum cover leaves the buyer short. For heavy or oversized loads, involve the underwriter before booking and review the lift and stowage plan with the team handling project cargo shipping.
Ask the forwarder or insurer for a cargo insurance quote and supply these inputs:
- Commodity description, and whether the goods are new or used
- Insured value, currency, and valuation basis
- Packing type and number of units
- Loading format, FCL or LCL
- Sales term and the point where risk transfers
- Pickup point, port or ports, and final delivery point
- Required clauses and any letter of credit wording
- Available shipping documents and any special handling, such as refrigeration, dangerous goods, or deck stowage
Illustrative example (not a customer case): A shipper sends packaged equipment under a sales term in which the buyer carries risk once the cargo is loaded. The default fits: the buyer arranges warehouse-to-warehouse cover in its own name for each shipment. The default flips if the sales term changes to a delivered arrangement in which the seller keeps risk until the destination. The seller then needs cover that runs to that delivery point and shows its own insured interest.
Key Takeaways
- Treat carrier liability and cargo insurance as separate protections; only the policy responds to the loss as the owner values it.
- Match the policy’s start and end points to the sales term and the freight scope before booking.
- Set the insured value basis in writing, and keep the invoice, packing list, and bill of lading consistent with the certificate.
- Compare quotes on value basis, clause level, deductible, and extensions, not on premium alone.
- Notify the insurer and carrier promptly after any loss, and send the insurer any general average notice before signing security.
FAQ
Is an insurance certificate the same as a policy?
No. A certificate evidences cover and summarizes key terms, while the policy or open cover contains the full wording, definitions, and exclusions. Banks and consignees usually ask for the certificate, but the policy governs a claim. Request the full wording when the cargo is unusual or valuable, and check that the certificate’s description and clauses match it.
Is sea freight insurance required for every ocean shipment?
There is no single rule for every trade. The requirement usually comes from the sales contract, a financing bank, or the importing country, and a few markets require cover placed with local insurers. Ask the forwarder or the relevant authority to confirm the current requirement for the destination before the policy is issued.
Does temperature-controlled cargo need different cover?
Usually yes. Standard clauses may not respond to spoilage after a refrigeration unit fails, so reefer cargo often needs an extension for machinery breakdown and temperature deviation. Give the underwriter the set temperature, pre-trip checks, and monitoring records, and confirm whether the policy requires a data logger before the container is loaded.
Do used or reconditioned goods affect eligibility?
They can. Insurers often apply conditions to used goods, such as limiting recovery to repair cost or excluding pre-existing damage. Declare the condition of the goods on the commercial invoice and in the quote request, and ask whether a pre-shipment inspection report is needed to support a later claim.
What if the vessel or route changes after the certificate is issued?
Tell the insurer as soon as you learn of the change. Policies often set conditions on vessel type and age, and a held-covered clause may keep cover in place if notice is given and any additional premium is agreed. Silence can give the insurer grounds to contest a later claim, so keep the carrier’s change notice on file.
What proof does an insurer expect after a loss?
Expect to submit a claim form, the bill of lading, the commercial invoice, the packing list, the certificate, and evidence of the damage. A surveyor’s report and written notice to the carrier usually follow. Gather these while the cargo is still available for inspection, since gaps in the file slow settlement.
How do you change the insured amount or consignee after issue?
Ask the insurer, or the forwarder arranging cover, to issue an endorsement before the cargo arrives. The request should state the correct value, party names, and bill of lading number. If a letter of credit applies, confirm with the bank that the amended certificate still complies before presenting documents.
Disclaimer: Transit times, cost explanations, customs information, and shipping suggestions on this page are general planning references, not a binding quotation, customs ruling, or delivery guarantee. Confirm the current route, service scope, charges, documents, and import requirements before booking.